Catch-up contributions in your fifties
Contribution room that went unused in your twenties is still sitting there, and your fifties are usually the decade when it is worth the most. Three things line up at once, and they do not line up again.
Why the fifties
- Income is usually at its peak, so a deduction is worth the most it will ever be worth. The value of an RRSP contribution is the marginal rate it saves.
- Room has accumulated. RRSP room carries forward indefinitely, so years of under-contributing during a mortgage or childcare are still available.
- The rate at withdrawal is finally estimable. The RRSP-versus-TFSA rule from episode 4 needs a retirement rate, and at 30 that is guesswork. At 55, with a retirement date and a balance in view, it is a calculation.
Both figures are worth looking up rather than estimating — the CRA reports your actual RRSP room on your notice of assessment, and your TFSA room in your online account. Estimating either is how over-contribution penalties happen.
The subtlety: contribute now, deduct later
A contribution and its deduction are separate events. You can contribute this year and carry the deduction forward to claim it in a later year — which is worth doing when a higher-income year is coming.
The money starts compounding immediately either way, so the only thing being deferred is the refund. For someone expecting a promotion, a bonus year, or a large severance, holding the deduction until the rate is higher is free money.
Priya’s window
Priya — 54, Ontario, single. $118,000 salary, $410,000 in her RRSP and $88,000 in her TFSA, planning to retire at 63.
Priya is 54 and retires at 63 — nine contributing years left. Her deduction is worth 37.2% today against a rate at withdrawal of 19.1%, which is about as favourable as the trade gets.
Directing five more points of salary into the RRSP across those years puts in $55,229 and adds $83,701 to a plan that otherwise ends at $360,723. The rate gap is real, but it is the smaller part of that: most of the gain is her own money, sheltered and compounding for another three decades.
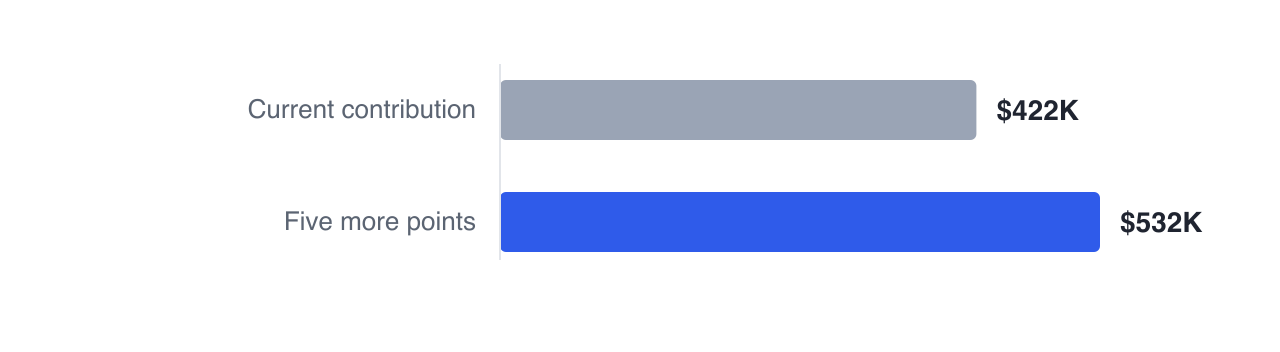
The short runway is also a warning. Nine years is not long, and the bigger RRSP is taxed on the way out: her lifetime tax rises. The gain is net of that — but it is a smaller bet than the same contribution would be at 30.
Where the TFSA fits
Accumulated TFSA room has no deduction attached, so its value is purely sheltered growth and clawback-invisible withdrawals. For someone in their fifties whose retirement income will sit near the OAS recovery threshold, filling TFSA room can be worth more than filling RRSP room — even though only one of them produces a refund.
That is the whole argument of episodes 3 and 4, arriving at the moment it becomes actionable. The decade when catch-up capacity and peak income coincide is also the decade when the withdrawal-rate estimate is finally reliable enough to use.
Raise your contribution and the projection re-runs live, reporting both the extra balance and what it does to your marginal rate in retirement — the two halves of the decision at once.
Next: the first year of retirement, in order, with nothing forgotten.
GlidePathEngine is an educational planning tool — not financial, investment, tax, or legal advice.