Downsizing: the math on freeing up home equity
Downsizing is the most commonly cited plan for turning a house into retirement income. It works, and the amount that actually arrives in the portfolio is reliably less than the difference between the two house prices.
What comes out of the proceeds
- Real estate commission on the sale — the largest single deduction, and a percentage of the full sale price rather than of the equity released.
- Legal fees on both transactions, plus land transfer tax on the purchase, which in some jurisdictions is substantial even on a smaller home.
- Moving costs, and the renovation or furnishing that almost always accompanies a move to a different kind of home.
- Any mortgage discharge cost if the existing mortgage is being broken early.
The tax side is at least simple. A principal residence gain is exempt, so the sale itself triggers no capital gains tax. That is the one part of the transaction that is genuinely free.
The ongoing effect, which is often larger
A smaller home costs less to run: lower property tax, lower insurance, lower utilities, less maintenance. That reduction repeats every year for the rest of the retirement and compounds against the required withdrawal.
For many households the annual saving is worth more over a thirty-year retirement than the lump sum released — and unlike the lump sum, it is not eaten by transaction costs. If downsizing is being evaluated purely on the equity released, the better half of the case is being left out.
What a home represents in a plan
Sam — 41, British Columbia, self-employed through a corporation. No employer pension, no home yet, and a company that pays them both salary and dividends.
Sam’s home is worth $713,469 at 60, and he still owes $212,428 on it — equity of $501,041, inside a net worth of $3,635,348. A real share of the household is in an asset producing no income — the situation episode 46 described.
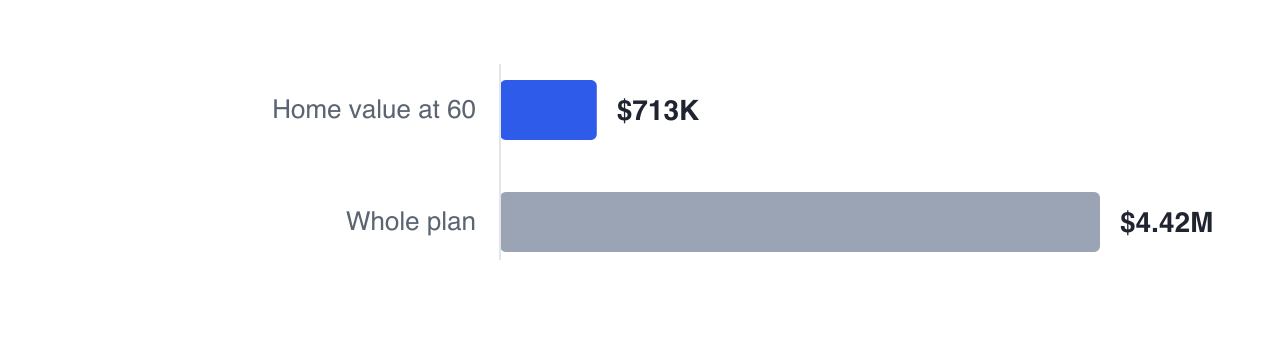
Downsizing to a home at, say, two-thirds of that value looks like it frees a third of the first bar. But the mortgage is paid off first: equity of $501,041 less a $475,646 home leaves $25,395 before a dollar of commission, land transfer tax, legal fees or renovation — worth estimating specifically rather than assuming.
The part that is not arithmetic
Leaving a long-held home is a significant life change, and the financial case rarely decides it on its own. Proximity to family, to health care, to a community — those usually matter more, and the money is a constraint rather than a reason.
Which is a good reason to model it in advance rather than in the year it is needed. A plan that works without downsizing has the move available as an option; a plan that requires it has a decision already made.
The real estate section takes a sell year for a property, so the projection releases the proceeds into your accounts in that year and you can see what the plan looks like with the move and without it.
Next: the reverse mortgage question — how it works and when it is the least-bad option.
GlidePathEngine is an educational planning tool — not financial, investment, tax, or legal advice.